Fewer Clients, More Leverage: How Oilfield Service Firms Are Quietly Winning the Bakken's Consolidation Era
The headlines from the Bakken over the past several years have followed a familiar script: two operators announce a merger, acreage maps are redrawn, and analysts debate the resulting scale advantages. What those headlines routinely omit, however, is the parallel story unfolding one layer beneath the operator tier—among the drilling contractors, pressure pumping firms, chemical suppliers, and equipment providers whose fortunes are being remade just as thoroughly, if far more quietly.
Service sector consolidation in the Bakken is not a new phenomenon, but its current phase carries different stakes. As the basin's operator count contracts and the surviving players grow substantially larger, service companies are discovering that the rules of engagement have fundamentally changed. Relationships that once turned on competitive bidding and short-cycle contracts are giving way to something more structural—and in many cases, more advantageous for the service firms that have positioned themselves correctly.
The Arithmetic of Fewer Customers
When a basin consolidates at the operator level, the immediate instinct among service providers is often defensive. Fewer clients can mean fewer contracts, greater pricing pressure, and heightened dependence on any single relationship. Those concerns are not unfounded. Service companies that failed to scale their own operations or differentiate their offerings have, in several documented cases, found themselves on the wrong side of vendor rationalization programs launched by newly merged operators seeking to streamline their supply chains.
But the arithmetic cuts both ways. Larger operators running multi-rig programs across expanded acreage positions require a level of operational consistency, logistical coordination, and technical integration that smaller, opportunistic service providers simply cannot deliver. The result is a natural selection process in which scale-capable service firms—those with sufficient equipment fleets, certified personnel, and data infrastructure—are being drawn into tighter, longer-term partnerships with the operators who now dominate the basin's activity.
Exclusivity arrangements, once rare in a market defined by spot-market pricing, are becoming a more visible feature of how leading Bakken operators structure their service relationships. For the service companies that secure such agreements, the trade-off is straightforward: accept pricing discipline in exchange for volume certainty and preferred vendor status.
Completion Services: The New Center of Gravity
No segment of the Bakken service sector has experienced this dynamic more acutely than completion services. As operators have pushed toward longer laterals, higher proppant loads, and increasingly complex completion designs, the technical demands placed on pressure pumping and perforating providers have risen sharply. The firms capable of executing high-intensity completions at scale—while simultaneously generating and interpreting the real-time data operators rely on for subsurface decision-making—occupy a fundamentally different market position than they did even five years ago.
Several national completion service providers have made targeted acquisitions of regional Bakken-focused firms specifically to capture this positioning. The goal is rarely about adding raw capacity. It is about acquiring local operational knowledge, established crew networks, and customer relationships that cannot be replicated through organic growth on a commercially relevant timeline. The acquired firms bring basin familiarity; the acquiring companies bring balance sheet strength and the ability to commit to the volume requirements that larger operators now demand.
The firms caught between those two tiers—too large to remain nimble, too small to absorb the capital requirements of competing for anchor contracts—are facing a genuine strategic dilemma. Some are pursuing niche specialization, focusing on technically demanding work that larger service companies are disinclined to price competitively. Others are exploring merger conversations of their own.
Drilling Contractors and the Long-Cycle Bet
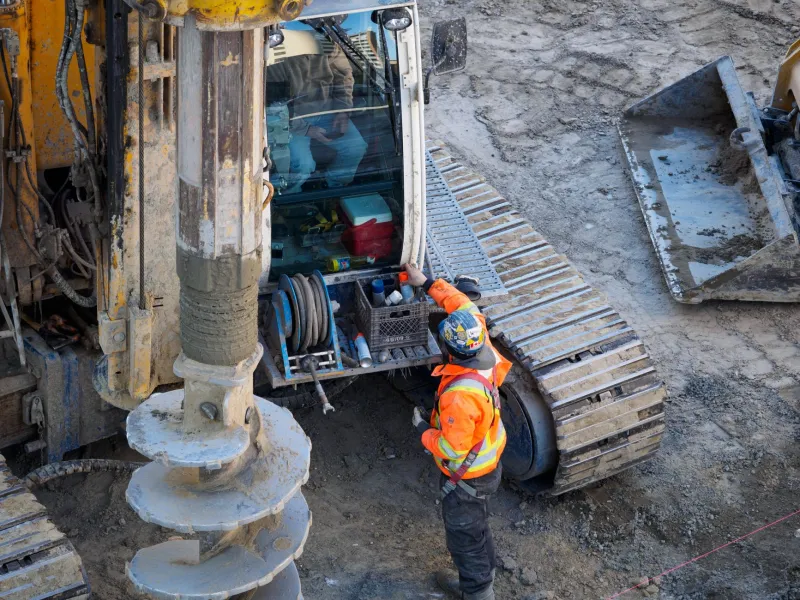
Among drilling contractors, the consolidation calculus is shaped by a different set of pressures. Rig economics in the Bakken have always been sensitive to utilization rates, and the shift toward larger operators with more predictable multi-well programs has made long-term rig contracts a more attainable objective for contractors willing to invest in the right equipment configurations.
The operators that emerged from recent mergers with expanded Tier 1 acreage positions have, in several cases, moved to lock in drilling capacity through multi-year agreements that provide contractors with the utilization visibility necessary to justify fleet upgrades and crew retention investments. For contractors, these arrangements represent a meaningful hedge against the volatility that has historically made Bakken drilling a boom-and-bust business.
The caveat is that operators are increasingly specific about what they expect in return. Automated drilling systems, real-time performance monitoring, and the ability to integrate contractor-generated data directly into operator workflows are no longer differentiators—they are baseline requirements for consideration in long-cycle contract discussions. Contractors that have deferred technology investment are discovering that the window to close that gap is narrowing faster than anticipated.
Supply Chain Compression and the Squeeze on Mid-Tier Vendors
Further down the supply chain, the consolidation dynamic is generating a more complicated picture. Chemical suppliers, rental equipment providers, and specialized service vendors that previously benefited from the diversity of a fragmented operator base are encountering a new reality: larger operators have both the purchasing power and the internal procurement sophistication to drive harder bargains and reduce vendor counts aggressively.
Vendor rationalization is not an abstract concept in the current Bakken environment. Newly merged operators are conducting systematic reviews of their supplier bases, identifying redundancies, and consolidating spending with fewer, larger vendors capable of providing standardized products and services across multiple operating areas. For mid-tier vendors without a clear differentiation story, the outcome of those reviews is often unfavorable.
The vendors navigating this environment most effectively share a common characteristic: they have invested in demonstrating measurable operational value rather than competing on unit price alone. Whether that value is expressed through reduced non-productive time, improved chemical performance data, or seamless integration with operator procurement systems, the ability to quantify contribution to well economics has become the primary currency of vendor relationship preservation.
The Power Dynamic Shifts—Gradually, Then All at Once
What is emerging in the Bakken service sector is not a clean narrative of winners and losers, but rather a structural realignment that is redistributing leverage across the supply chain in ways that will take several more years to fully manifest. The service firms that recognized the consolidation trend early and invested in scale, technical capability, and customer integration are accumulating advantages that compound over time. Those that treated consolidation as a temporary disruption rather than a structural shift are finding the competitive ground beneath them increasingly unstable.
For operators attending industry forums and planning sessions, the implications are equally significant. The service company landscape they navigate in 2026 will look materially different from the one that existed in 2022. The number of credible, full-service partners capable of supporting large-scale Bakken programs will be smaller, and the terms on which those relationships are structured will reflect that scarcity.
Consolidation, it turns out, is not solely an operator story. The companies that keep the rigs turning and the completions flowing are writing their own version of it—and in some corners of the basin, they are writing it on considerably more favorable terms than the headlines would suggest.