Pipelines, Ponds, and Profits: The Rise of Water Infrastructure as a Bakken Competitive Differentiator
The Fluid Nobody Talks About—Until It Stops Moving
For every barrel of crude oil lifted from a Bakken formation, operators typically handle several barrels of produced water. That ratio has been climbing as wells age and water cuts increase across the basin. Yet for years, produced water was treated as an operational nuisance rather than a strategic variable—something to be disposed of as quickly and cheaply as possible, with minimal investment in the infrastructure required to do it well.
That calculus is changing. Across North Dakota and into Montana, water logistics constraints are now influencing decisions that were once driven entirely by geology and crude economics. Where a well gets drilled, how quickly it can be brought online, and whether a particular lease position is economically viable are increasingly questions with water management answers.
The Bakken's invisible infrastructure is becoming visible—and operators who recognized this shift early are reaping the benefits.
Disposal Bottlenecks and the Well Placement Problem
The most immediate consequence of inadequate water infrastructure is operational friction. When disposal capacity is constrained—whether due to limited pipeline connectivity, fully subscribed injection wells, or regulatory restrictions on new disposal permits—operators face a set of unattractive choices. They can haul water by truck, which is expensive and weather-dependent. They can curtail production to match available disposal capacity. Or they can delay completions until infrastructure catches up.
None of these options are acceptable in a cost-disciplined operating environment. Trucking water adds meaningfully to per-barrel lifting costs, particularly for wells in basin-edge locations where road infrastructure was not designed for industrial volumes. Curtailment destroys value on assets that have already absorbed significant capital. And delayed completions erode the internal rate of return on every well in the queue.
What this means in practice is that water disposal capacity—or the lack of it—is quietly shaping well sequencing decisions across the basin. Operators with owned or contracted disposal infrastructure in a given area can move faster and cheaper than competitors who are exposed to spot market disposal rates or trucking logistics. That speed advantage compounds over time: more wells completed per year, lower finding and development costs, and a tighter feedback loop between capital deployment and production growth.
Recycling Economics: From Compliance Cost to Revenue Opportunity
Beyond disposal, a growing number of Bakken operators are evaluating produced water recycling as both an economic and reputational strategy. The core proposition is straightforward: rather than disposing of produced water in injection wells, treat it to a standard suitable for reuse in hydraulic fracturing operations. If the treatment cost is lower than the combined cost of freshwater sourcing and disposal, recycling generates net savings.
In certain parts of the Bakken, that equation is increasingly favorable. Freshwater is not scarce in North Dakota the way it is in the Permian Basin, but sourcing, transportation, and storage costs are not trivial. For operators running high-volume completions programs with consistent water demand, a reliable supply of treated produced water can reduce freshwater dependency and lower overall completion costs.
The reputational dimension matters as well. As environmental scrutiny of oil and gas operations increases—from regulators, investors, and the communities that host Bakken activity—demonstrating responsible water stewardship has become a meaningful component of the social license to operate. Operators who can point to active recycling programs are better positioned in permitting processes, landowner negotiations, and ESG-focused capital markets.
The Midstream Opportunity in Water
For midstream companies, the emerging water logistics landscape represents an underappreciated growth opportunity. The traditional Bakken midstream business model was built around crude gathering, natural gas processing, and NGL fractionation. Water infrastructure was largely left to operators to manage on their own or through small, specialized disposal companies.
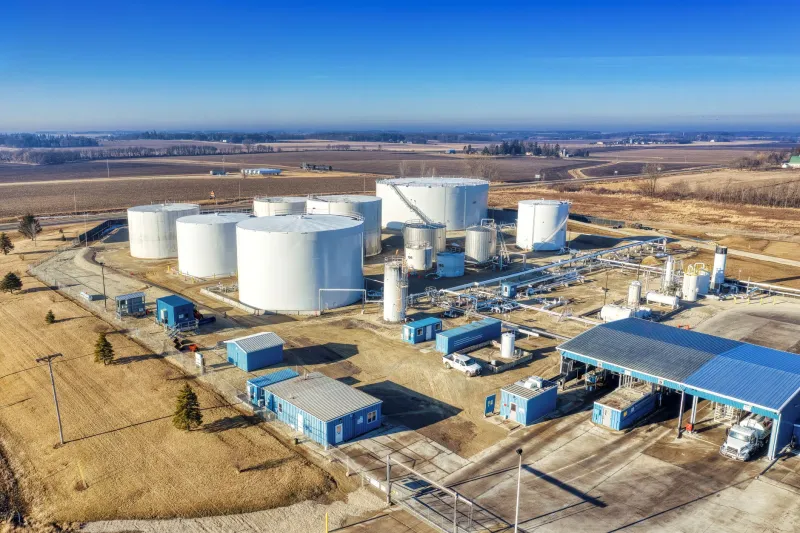
That model is shifting. Several midstream players have begun investing in dedicated produced water gathering systems—networks of pipelines connecting wellpads to centralized disposal or treatment facilities—that mirror the structure of crude gathering systems. The economic logic is familiar: replace expensive, variable trucking costs with lower-cost, fixed-infrastructure solutions, and charge gathering fees that generate stable, fee-based revenue.
For operators, the appeal of third-party water gathering is the same as the appeal of third-party crude gathering: capital efficiency. Building and operating water infrastructure is not a core competency for most producers. Outsourcing it to a specialized midstream provider frees up capital for drilling and completions while converting a variable cost into a more predictable contractual obligation.
The challenge for midstream investors is that water gathering economics are more complex than crude gathering economics. Produced water volumes fluctuate significantly over a well's life, disposal regulations vary by location and can change, and the creditworthiness of water gathering customers depends on the same commodity price dynamics that affect crude gathering. These risks are manageable, but they require a more sophisticated underwriting approach than the traditional midstream model demands.
Integrated Water Strategy as a Competitive Framework
The operators gaining the most from the water logistics shift are those who have developed what might be called an integrated water strategy—a deliberate approach that connects well planning, disposal infrastructure, recycling capabilities, and midstream relationships into a coherent operational framework.
This integration manifests in several ways. At the planning stage, integrated operators assess disposal capacity alongside drilling economics when evaluating well locations. They secure disposal contracts or build disposal infrastructure in advance of drilling campaigns, rather than scrambling for capacity after wells are online. They track water volumes and costs with the same rigor applied to crude production and lifting costs.
At the portfolio level, integrated water strategies create optionality. Operators with excess disposal capacity can generate revenue by accepting third-party volumes. Those with recycling infrastructure can offer treated water to other operators in their operating area. Both capabilities transform what was once a pure cost center into a potential profit center—and in a business where every dollar of cost reduction per barrel matters, that transformation is strategically significant.
What the Bakken Conference Sees Ahead
The conversation about water in the Bakken is no longer confined to environmental compliance discussions. It has moved into boardrooms, capital allocation meetings, and acreage acquisition negotiations. The operators who treat water logistics as a core strategic variable—rather than a downstream operational afterthought—are building structural cost advantages that will outlast any single commodity price cycle.
For midstream investors, the water infrastructure gap in parts of the basin represents a genuine deployment opportunity, provided they can navigate the regulatory and commercial complexity involved. And for the broader Bakken industry, the maturation of water logistics networks will be one of the defining infrastructure stories of the next decade—as consequential, in its own way, as the build-out of crude gathering systems that enabled the basin's original production boom.